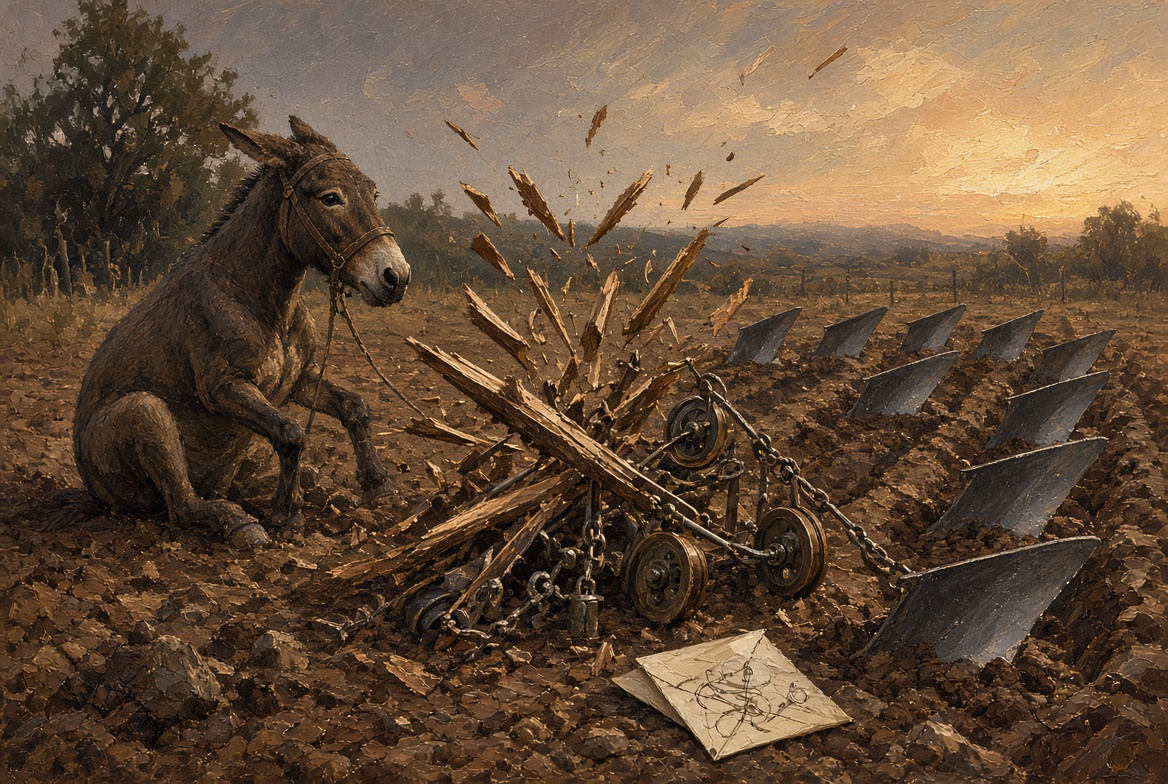
A neighbor of mine down in Callaway County once claimed he had rigged a cedar harness capable of letting a single Missouri mule plow five separate furrows at the exact same instant. He drew the rigging on the back of an envelope, full of pulleys, counterweights, and brass swivels that looked convincing enough to anyone who had never handled a plow. The contraption was a marvel of mechanical efficiency on paper. Out in the back forty, however, the mule took one step, felt the impossible drag of five steel points biting into stony clay, sat down in the dirt, and kicked the singletree into matchwood. The contraption was a marvel of mechanical efficiency on paper. Out in the back forty, however, the mule took one step, felt the impossible drag of five steel points biting into stony clay, sat down in the dirt, and kicked the singletree into matchwood.
I think of that mule every time a bright young software architect tries to explain the modern gospel of restaking. They do not talk about mules, of course. They talk about pooled economic security, decentralized trust marketplaces, and unlocking idle liquidity. Yet underneath the clean fonts and mathematical whitepapers sits the exact same rural delusion: the conviction that clever engineering can coax five days of hard labor out of a single sack of oats.
When you stake an asset on a digital ledger, you are posting a bond. You lock up your capital to swear that the bookkeeper will not cook the accounts, accepting a modest return for your trouble. But speculative markets cannot bear the sight of idle capital. The engineer looks at that locked bond, feels a pang of financial grief, and asks why that same deposit cannot also guarantee an off-chain oracle, a cross-network bridge, two transaction rollups, and a data-availability layer. They call it efficiency. A seasoned bank examiner, looking over his spectacles on a dreary Friday afternoon, would call it what it has always been: rehypothecation with an algorithm attached.
Pledging the Family Silver by Lunchtime
The practice of promising the same asset to multiple creditors is older than double-entry bookkeeping, and it has never once ended in a parade. In the late nineteenth century, speculative rail syndicates used to pledge the very same stretch of track, iron rails, and cross-ties to three different sets of British bondholders. Every syndicate clerk knew that so long as the freight trains ran on schedule and the wheat harvest fetched top dollar, nobody would bother to walk the line and count the spikes. The trouble arrived only when the wheat rotted in the silo and three furious bank managers showed up at the depot on the same Tuesday morning, each waving a parchment deed to the exact same water tower.
Restaking attempts the same sleight of hand in the digital ether. An investor takes his base security deposit, wraps it in a synthetic receipt, and deposits that receipt into a second protocol, which issues a third receipt to be pledged into a third protocol. Each layer promises an incremental sliver of yield. By the time the stack is four tiers high, the investor imagines he has discovered an engine of pure wealth creation.
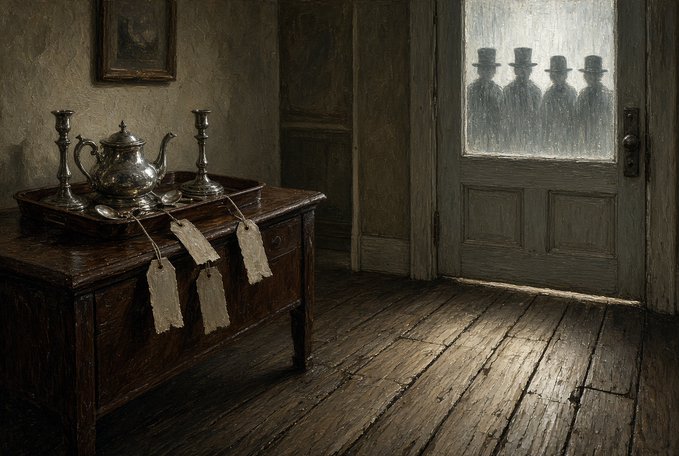
When you pledge the family silver to four different pawnbrokers before noon, you have not multiplied the silver. You have only multiplied the knocks at your front door.
The fatal flaw in this parlor trick is that the underlying asset never grows. It does not sprout roots. It does not build a warehouse or dig an irrigation ditch. It remains a single digital deposit, bearing the impossible psychological weight of multiple guarantees. The yield being collected is not the fruit of productive enterprise; it is an insurance premium collected by an amateur who has entirely forgotten that he is the underwriter.
The Alchemy of Imaginary Redundancy
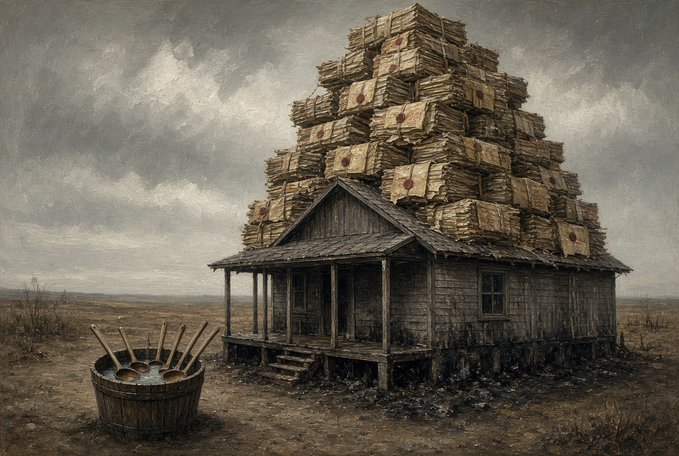
Wall Street spent several decades refining this exact brand of alchemy prior to the autumn of 2008. They bundled mortgages, insured the bundles, sold claims on the insurance, and treated the entire tottering pyramid as though it were safer than the individual houses holding it up. The prevailing theory was that diversification cured all sins. If one homeowner defaulted, the broader pool would hardly notice the drop of water missing from the bucket.
Restaking operates on an even shakier premise, because the risks are not uncorrelated. They are intimately, mechanically tied together. Consider what happens when an asset is restaked across five distinct networks:
- Slashing is absolute: Unlike a traditional loan where a debtor can renegotiate terms or file for bankruptcy protection, smart contracts execute without mercy. If a validator misbehaves, the penalty burns the principal immediately.
- Fault propagation: A software bug in an obscure, experimental bridge can trigger a slashing event that liquidates the collateral underpinning four entirely unrelated services.
- Liquidity mirages: The synthetic tokens issued against restaked assets trade freely until panic strikes, at which point the market discovers that you cannot redeem five claims against one deposit simultaneously.
When one contract burns the principal to cover a failure, the remaining four contracts do not receive a polite letter of apology. They receive a fatal arithmetic exception. The security they thought they had purchased vanishes into thin air, leaving every dependent service naked to attack at the precise moment when panic is highest.
The Fundamental Distinction Between Yield and Risk
To understand why this structure makes the floorboards groan, one must step away from the terminal and ask where legitimate financial returns actually originate. A genuine dividend represents a share of surplus value created by human labor, capital equipment, and honest commerce. When a freight line carries coal from Pennsylvania to the docks of Philadelphia, the factory owner pays the railroad because the coal is worth more at the blast furnace than it was in the ground. That surplus clears the accounts, pays the track gangs, and leaves a nickel of profit for the shareholder.
In the quiet corners of restaking, no coal is moved. No blast furnace is lit. The yield does not represent surplus cash flow generated by customers paying for a good they cannot live without. Instead, it is a payment made in exchange for assuming systemic fragility. The protocols paying for this pooled security are often paying because they cannot attract authentic capital on their own merits. They are borrowing the reputation of established deposits to paper over their own apparent lack of economic foundation.
Collecting five percent here and three percent there for staking the same collateral across multiple systems looks like pure cleverness during a bull market. The sun shines, token prices march upward, and the Joists do not make a sound. But leverage stacked that high does not give fair warning. It does not warp slowly over several seasons. It snaps all at once, precisely when a gust of real-world distress hits the house.
Leaving the Barn Before the Joists Give Way
I have lived long enough to see half a dozen financial revolutions promise that old-fashioned balance sheet math had been rendered obsolete by new plumbing. In every instance, the innovators believed they had found a loophole in the law of conservation of capital. They believed that if you routed an obligation through enough pipes, valves, and digital relays, the original risk would evaporate into the atmosphere like steam.
It never does. The risk simply accumulates in the joints of the structure, waiting for an unexpected frost. Restaking does not eliminate the cost of security; it merely hides the underwriting debt until the day of reckoning. A ledger can be programmed to perform astonishing feats of coordination, but it cannot make one dollar do the duty of five when the liquidation orders begin to print.
For my own part, I prefer investments that stand on their own foundation without needing to be tied to four other wagons to keep from rolling downhill. When an asset offers me multiple streams of income derived from the exact same collateral, I do not reach for my checkbook. I reach for my hat, walk out of the room, and let the innovators enjoy the thrill of discovering how much weight an over-leveraged joist can bear before the whole floor drops into the cellar.